How could a potential Iran Israel war impact your retirement if markets react the way they have in past conflicts? It’s a real question for anyone in the retirement red zone, because global tension doesn’t stay global for long. Markets respond immediately, often with sharp swings, and those swings hit hardest when you’re within five to ten years of retirement. This is the stage where a single bad year can permanently reshape your income, your withdrawal strategy, and the long‑term stability of your plan.
You can’t control what happens overseas, but you can control how prepared your retirement strategy is for uncertainty. Conflict, volatility, inflation, and taxes tend to move together, and that combination creates real pressure on portfolios that aren’t built for downside protection. When the world gets unpredictable, your retirement plan needs structure, balance, and tools that can absorb shocks while still giving you room to grow.
Rising Iran Israel tension creates the kind of uncertainty that markets react to immediately, and those reactions hit hardest when you are in the retirement red zone. This five to ten year window around retirement is where volatility becomes more than an inconvenience. It becomes a direct threat to your income, your withdrawal strategy, and the long‑term stability of your plan. Markets do not wait for clarity, and geopolitical conflict is one of the fastest ways to trigger sudden swings that are difficult to recover from when you no longer have decades to rebuild.
The real issue is not predicting what will happen overseas. It is understanding how quickly global conflict can ripple into your portfolio through volatility, inflation pressure, and shifting tax policy. When the world becomes unpredictable, your retirement strategy needs to be built for resilience, with enough protection to absorb shocks and enough growth potential to keep your income on track.
The retirement red zone is the five to ten years before and after you stop working, and it is the period when market losses matter most. You no longer have decades to recover, and withdrawals can turn even a modest downturn into a permanent reduction in lifetime income. Volatility tied to rising Iran–Israel tension can therefore have a much bigger impact on someone nearing retirement than on someone still in the accumulation phase.
This stage requires a shift in strategy. Growth still matters, but protection becomes just as important. Your portfolio needs enough stability to absorb sudden swings and enough structure to keep your income plan on track, even when global events create uncertainty.
Geopolitical conflict rarely affects just one part of the economy. When Iran Israel tension rises, markets often react with volatility, inflation pressure tends to build, and governments begin preparing for higher future spending. That combination can create a challenging environment for retirees who rely on stable income and predictable tax exposure.
Market swings can reduce portfolio values at the exact moment you need consistency. Inflation can erode purchasing power faster than expected. And increased government spending during global conflict often leads to higher taxes down the road, which directly affects retirees drawing from taxable accounts. Understanding how these forces interact helps you build a retirement plan that can stay steady even when the world is not.
Protected‑growth strategies give retirees a way to steady their portfolio when traditional bonds are not doing their job. During periods of global tension like the current Iran Israel uncertainty, bonds can lose value, deliver weak yields, or move unpredictably when interest rates and inflation shift at the same time. That leaves a gap for people in the retirement red zone who need stability more than ever.
These strategies link your growth to a market index without exposing your principal to market losses. When the index rises, you capture a portion of the upside. When it falls, your principal stays protected. This creates a smoother path into retirement by reducing the impact of sudden downturns while still allowing your plan to move forward. It is a way to keep growing without taking on the full weight of market volatility.
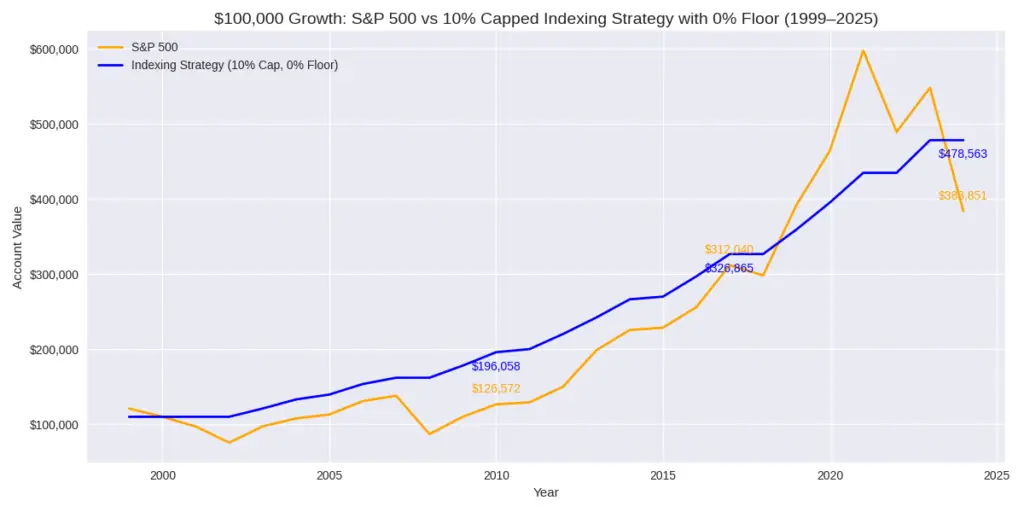
Exhibit: $100,000 Growth in S&P 500 vs Indexing Strategy (1999–2025): This exhibit compares $100,000 invested in the S&P 500 with an indexing strategy capped at 10 percent and floored at 0 percent. The S&P 500 line shows full market volatility, while the indexing strategy grows steadily, never declining in down years. Key points in 2010, 2017, and 2024 highlight how the indexing approach avoided losses yet kept pace with long‑term growth. A hypothetical 30 percent drop in 2025 illustrates how the floor protects value, underscoring the strategy’s role as a powerful diversification tool.
Stress‑testing your retirement plan is the final step that turns all of this from theory into protection. Global tension, market swings, inflation pressure, and future tax changes are all outside your control, but you can measure how well your plan holds up if any of them get worse. A good stress test shows what happens to your income if markets drop early in retirement, if inflation stays elevated, or if taxes rise during your distribution years.
The goal is clarity. You want to know whether your current mix of growth, protection, and income sources can withstand a few bad years without forcing you to change your lifestyle. When you can see the weak spots, you can fix them before they become real problems. And when your plan holds up under pressure, you gain the confidence that you are ready for whatever the world throws at you.
Global tension will always create uncertainty, but your retirement plan should be built to stay steady even when the world is not. When conflicts like the Iran Israel situation push markets into sudden swings, retirees are the ones who feel it most. This is the stage where timing risk, inflation pressure, and future tax changes can all collide at once and where having the right balance of growth, protection, and income structure becomes the difference between a plan that bends and a plan that breaks.
To know whether your strategy is truly prepared, schedule a complimentary retirement stress test with our team. We’ll analyze your current plan, identify any weak spots, and show you exactly how your income holds up under real‑world pressure so you can move forward with clarity and confidence.
M&M Wealth Associates values your privacy and is committed to helping make your experience with our website safe, secure, and informative. This Privacy Policy explains how we collect, use, and share information you provide when accessing or using our website.
This website is intended for use by individuals who are at least 18 years of age and who are accessing the website from within the United States.
By using this website or submitting information through it, you acknowledge that:
This Privacy Policy is incorporated into and subject to the website’s Terms of Use.
We may collect both personally identifiable information (“PII”) and non-personally identifiable information (“Non-PII”).
Examples include:
Examples include:
For purposes of this Privacy Policy, both categories may be referred to collectively as “Information.”
We may collect information when you:
We may also automatically collect certain information through cookies, browser information, analytics tools, and similar technologies.
Information automatically collected may include:
Cookies may be used to improve website functionality, personalize user experiences, and support website analytics.
Information collected through the website may be used to:
We may share information with service providers and business partners who assist us in operating our business and servicing client needs.
We may also disclose information when:
By submitting information through this website, you consent to being contacted through the information you provide, including by:
You may opt out of future promotional communications at any time.
To request removal from promotional communications, please contact:
M&M Wealth Associates
2900 S Harbor Blvd, Suite 225
Santa Ana, CA 92704
Phone: (714) 494-9515
Please allow up to 10 business days for processing. Administrative or legally required communications may still be sent when permitted by law.
We maintain reasonable administrative, technical, and physical safeguards designed to protect information from unauthorized access, use, disclosure, alteration, or destruction.
However, no method of transmission or storage is completely secure, and we cannot guarantee absolute security.
If a security incident occurs, we may notify affected individuals electronically when permitted by law.
If you believe website security has been compromised, please contact us at:
(714) 494-9515
M&M Wealth Associates reserves the right to update or modify this Privacy Policy at any time.
Changes become effective immediately upon posting to the website. Continued use of the website constitutes acceptance of any updated Privacy Policy.
If you have questions regarding this Privacy Policy, please contact:
M&M Wealth Associates
2900 S Harbor Blvd, Suite 225
Santa Ana, CA 92704
Phone: (714) 494-9515